
BNPL Payment Setup Process for Retailers: 2026 Guide
July 2, 2026
TL;DR:
- Implementing BNPL involves connecting your store to a provider’s credit infrastructure while ensuring all prerequisites are met.
- This setup allows retailers to receive funds within 1-3 days and transfers credit risk to the provider.
The BNPL payment setup process is the sequence of technical and business steps a retailer completes to integrate Buy Now, Pay Later options at checkout, expanding customer purchasing power and increasing conversion rates. Formally called installment payment integration, this process connects your store to a BNPL provider’s credit infrastructure, so shoppers can split purchases into smaller payments while you receive the full sale amount upfront. Retailers receive funds within 1–3 business days after authorization, minus the merchant discount fee. The BNPL provider absorbs all consumer credit risk, meaning your business is protected from customer defaults the moment a transaction is authorized and settled.
What do you need before starting the BNPL payment setup process?
Getting the prerequisites right saves you days of troubleshooting later. Before you touch a plugin or API key, confirm you have the following in place.
Business and account requirements
- Legal business entity: A registered business (LLC, corporation, or sole proprietor with an EIN) is required by every major BNPL provider.
- Business bank account: Settlements are deposited directly. A personal account will not pass merchant onboarding.
- Tax identification: Your EIN or SSN is required for underwriting and compliance checks.
- Valid eCommerce or POS platform: Your store must run on a supported platform. Most BNPL providers support Shopify, WooCommerce, Magento, BigCommerce, and custom API builds.
Choosing the right BNPL provider
Provider selection shapes your fee structure, customer eligibility rules, and integration complexity. Review contract terms carefully before signing. Key variables include the merchant discount rate (MDR), minimum and maximum order values, supported geographies, and refund handling policies. Providers also differ in their installment structures. The standard Pay in 4 model splits a purchase into four equal payments over six weeks, typically interest-free for the consumer. Longer plans may carry interest rates of 15–24% APR, which affects how you market the option to customers.
Technical tools you will need
| Tool | Purpose |
|---|---|
| API credentials | Authenticate your store with the BNPL provider’s system |
| Platform plugin or app | Handles UI rendering and checkout flow on Shopify, WooCommerce, etc. |
| Payment gateway config | Routes BNPL transactions alongside your existing card processing |
| Sandbox/test environment | Validates the full transaction path before going live |
| Webhook endpoints | Receives real-time updates on payment status, refunds, and cancellations |
Pro Tip: Request sandbox credentials from your BNPL provider before signing the contract. Testing the integration in a staging environment reveals compatibility issues early, before you are locked into terms.
How to integrate BNPL payment options step by step
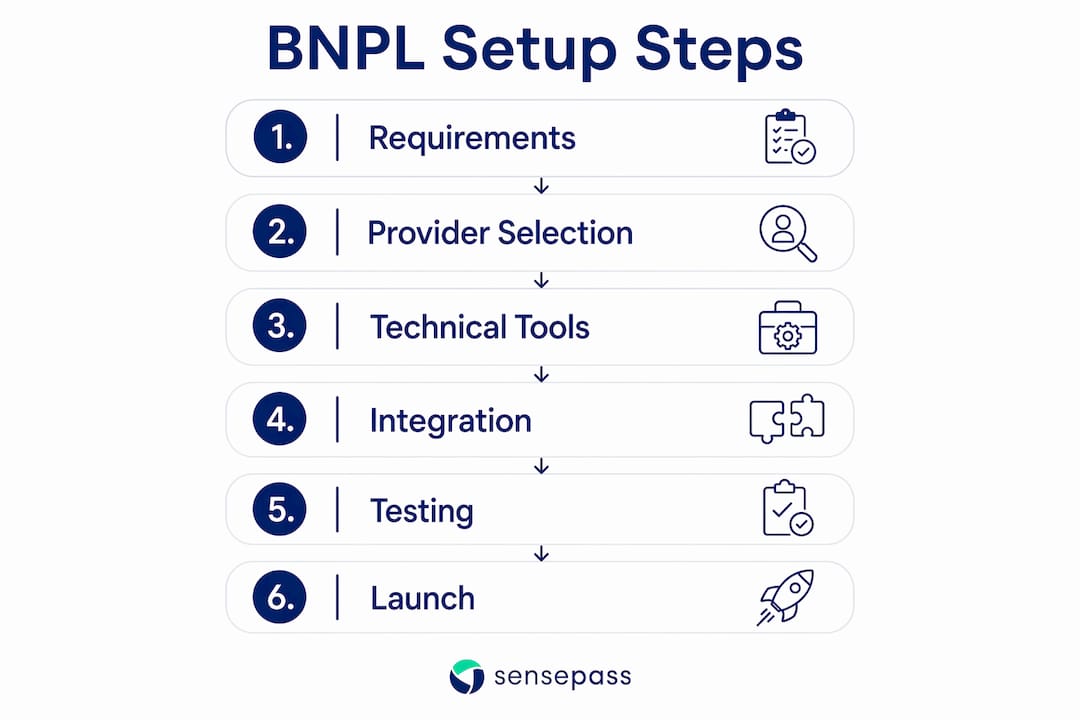
The buy now pay later setup follows a consistent pattern across platforms, even though the specific tools differ. Work through these steps in order.
-
Apply for a merchant account with your chosen BNPL provider. Submit your business details, bank account information, and expected monthly volume. Approval typically takes 1–5 business days. You will receive API keys, a merchant ID, and access to a merchant dashboard.
-
Install the provider’s plugin or app on your platform. On Shopify, Shop Pay Installments activates with a single toggle in the Shopify Payments admin settings. No app installation is required. On WooCommerce, BNPL requires manual plugin installation, API key insertion, eligibility mapping, and theme compatibility checks. Magento and custom platforms use direct API integration.
-
Insert your API credentials. In your platform’s payment settings or plugin configuration panel, enter the public and secret API keys provided by your BNPL provider. These keys authenticate every transaction request your store sends.
-
Map product and order eligibility. Most providers enforce minimum and maximum order values. Configure these thresholds in the plugin settings so the BNPL option only appears for qualifying cart totals. Mismatched eligibility rules are one of the most common causes of checkout display errors.
-
Configure installment messaging on product pages and cart. On-site installment banners on product pages improve customer understanding and increase BNPL adoption. The messaging should display the per-installment amount dynamically based on the product price. Most plugins generate this automatically once configured correctly.
-
Run full transaction tests in sandbox mode. Test a complete checkout, an authorization, a refund, and a cancellation before going live. This step catches webhook failures, display bugs, and edge cases that only appear under real transaction conditions.
-
Go live and monitor the first 48 hours closely. Watch your merchant dashboard for failed authorizations, missing settlements, and customer support tickets related to checkout confusion.
Pro Tip: If you run a physical retail location alongside your online store, connect your BNPL setup to your POS system as well. Sensepass supports Klarna at Shopify POS and other BNPL providers in-store, so your checkout experience stays consistent across every channel.
How does the BNPL payment transaction workflow work?
Understanding what happens behind the scenes helps you set accurate expectations for cash flow, fees, and customer experience. The BNPL payment process workflow moves through four distinct stages.
Stage 1: Instant credit assessment. When a customer selects a BNPL option at checkout, the provider runs a real-time credit check. This typically takes seconds and uses soft inquiry methods that do not affect the customer’s credit score. The provider either approves or declines the installment plan instantly.
Stage 2: Authorization and merchant settlement. Once approved, the BNPL provider authorizes the full purchase amount and commits to paying your store. You receive the full sale amount minus the merchant discount rate. BNPL merchant fees range from 1.5% to 8% per transaction, which is generally higher than standard credit card processing fees of around 2%. Settlement lands in your bank account within 1–3 business days.
Stage 3: Risk transfer to the provider. The BNPL provider now owns the consumer receivable. Merchants are fully protected from consumer defaults once the transaction is authorized and settled. This is a structural advantage over offering in-house financing or net terms. Your revenue is secured regardless of whether the customer completes their installment payments.
Stage 4: Consumer repayment management. The provider collects installment payments directly from the customer according to the agreed schedule. Late payment fees and interest charges (on longer plans) are the provider’s responsibility to manage. Your store has no operational role in consumer collections.
Key insight: The merchant discount rate is the price you pay to transfer credit risk. For most retailers, the uplift in average order value and conversion rate more than offsets the higher fee compared to card processing. Review your payment processing fees regularly to confirm the math holds for your product mix.
Common troubleshooting tips for BNPL setup
Even a well-planned BNPL integration hits friction points. These are the issues retailers encounter most often, and how to resolve them.
-
BNPL option not appearing at checkout. Check that the cart total falls within the provider’s minimum and maximum order thresholds. Confirm the plugin is active and that your API keys are entered correctly. On WooCommerce, theme conflicts can suppress the payment option display entirely.
-
Installment banners showing incorrect amounts. This usually means the dynamic messaging script is not reading the product price correctly. Verify that the plugin version is current and that your theme does not override the price display element.
-
Refunds not processing correctly. Test refund flows before going live. Some providers require refunds to be initiated through their merchant dashboard rather than your platform’s native refund tool. Misconfigured refund paths lead to customer disputes and delayed credits.
-
Missed webhook notifications. If your system is not receiving payment status updates, check that your webhook URL is correctly registered in the provider’s dashboard and that your server accepts POST requests from the provider’s IP range.
-
Low BNPL adoption after launch. The most common cause is poor on-site messaging. Add installment banners to product pages, the cart page, and the checkout confirmation screen. Customers who do not see the option early in their shopping session rarely select it at checkout.
Pro Tip: Set a 30-day review after launch. Pull your BNPL conversion rate, average order value for BNPL transactions versus card transactions, and the share of total revenue coming through installments. These three numbers tell you whether the integration is working or needs adjustment. Sensepass provides a retail financing setup guide with performance benchmarks to help you interpret your results.
Key Takeaways
A successful BNPL integration requires verified prerequisites, platform-specific configuration, and active performance monitoring from day one.
| Point | Details |
|---|---|
| Prerequisites matter | Confirm your business entity, bank account, and platform compatibility before applying to any BNPL provider. |
| Settlement is fast | Merchants receive funds within 1–3 business days, with the BNPL provider absorbing all consumer credit risk. |
| Fees vary significantly | Merchant discount rates range from 1.5% to 8%; calculate the net impact on your margins before committing. |
| Platform setup differs | Shopify enables BNPL with a single toggle; WooCommerce requires manual plugin installation and API configuration. |
| Test before going live | Run complete transaction flows including refunds and cancellations in sandbox mode to prevent checkout errors. |
Why I think most retailers underestimate the BNPL setup process
Most retailers treat BNPL as a simple plugin install. They toggle it on, see the option appear at checkout, and consider the job done. That approach leaves serious money on the table and creates real operational risk.
The part that gets skipped most often is the fee math. A merchant discount rate of 5–8% sounds manageable until you apply it to a low-margin product category. I have seen retailers activate BNPL across their entire catalog and quietly erode margin on items where the conversion uplift did not compensate for the fee. The fix is simple: segment your catalog and enable BNPL selectively on higher-margin or higher-ticket items where the average order value increase justifies the cost.
The second underestimated area is the omnichannel gap. Retailers who set up BNPL online but leave their physical stores on a separate payment system create a fragmented customer experience. A shopper who uses installments online and then visits your store expects the same option. Closing that gap requires an omnichannel payment strategy that connects your eCommerce and POS environments under a single payment layer.
The third thing I would flag is contract review cadence. BNPL provider terms change. Fees shift, eligibility rules tighten, and settlement windows can extend. Build a quarterly review into your operations calendar. Check your MDR against current market rates, verify that your refund integration still works after platform updates, and confirm your compliance with any new consumer protection regulations your provider has adopted.
BNPL is a genuinely powerful tool for retailers. The credit risk transfer alone makes it worth serious consideration. But it rewards retailers who treat it as a managed financial product, not a set-and-forget checkout feature.
— Vlad
Sensepass makes BNPL integration part of a complete payment setup
Retailers who want BNPL working across every channel, not just one platform, need a payment layer that connects everything. Sensepass is a processor-agnostic payment orchestration platform that integrates with NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, Dynamics365, and more.
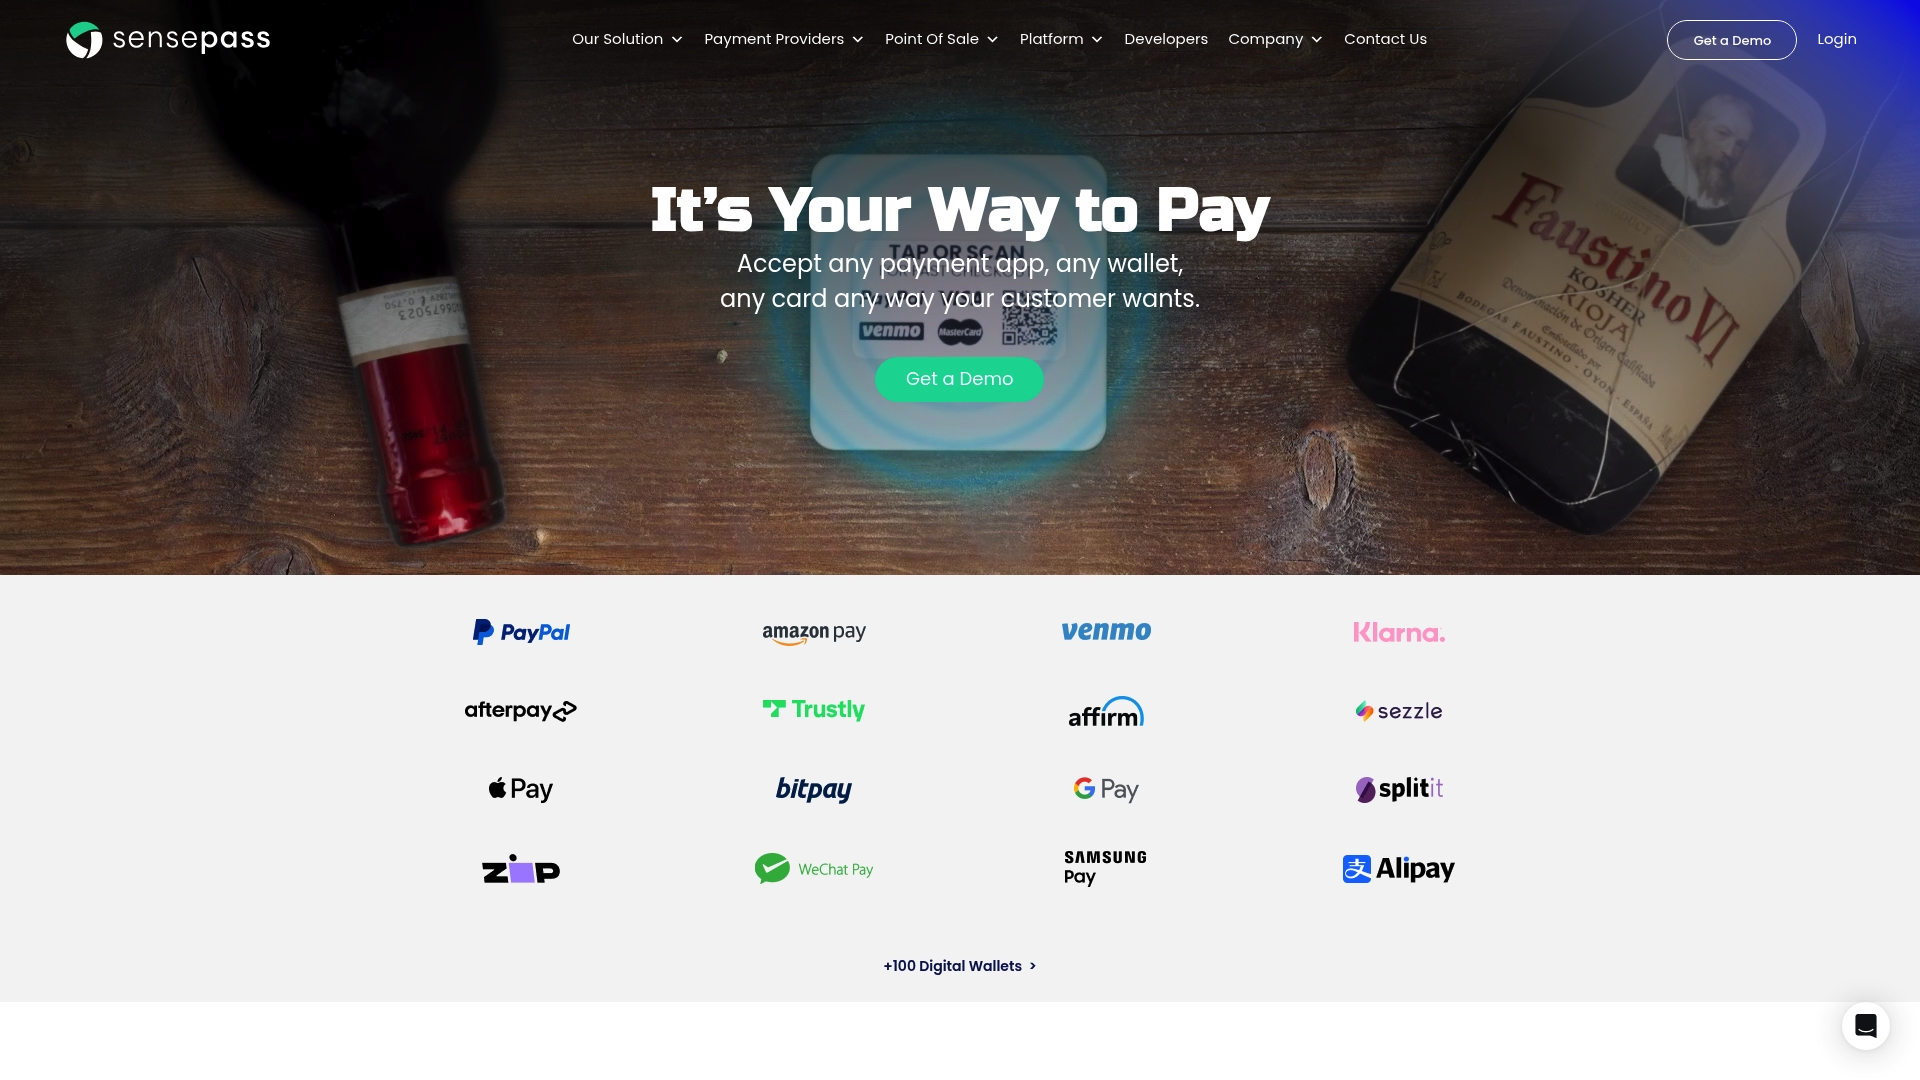
Sensepass supports BNPL providers including Klarna, Afterpay, ZIP, Sezzle, and Splitit alongside digital wallets like Apple Pay, Google Pay, PayPal, Venmo, Alipay, WeChat, and Amazon Pay. Financing options include WeGetFinancing and Affirm. Crypto payments via BitPay and Coinbase and Pay by Bank through Trustly and LinkMoney are also supported. With access to 50+ card processors, you choose the processing relationship that fits your business. Explore how Sensepass supports your omnichannel payment setup to bring BNPL, wallets, and card processing together under one integration.
FAQ
What is the BNPL payment setup process?
The BNPL payment setup process is the sequence of steps a retailer completes to integrate installment payment options at checkout, including merchant account creation, platform plugin configuration, API key setup, and transaction testing.
How long does BNPL integration take?
Integration time varies by platform. Shopify merchants can enable BNPL in minutes using a native toggle, while WooCommerce and custom API integrations typically take one to three days including testing.
When do merchants get paid with BNPL?
Merchants receive the full sale amount minus the merchant discount fee within 1–3 business days after the transaction is authorized, regardless of the customer’s installment schedule.
What fees do merchants pay for BNPL?
Merchant discount rates for BNPL range from 1.5% to 8% per transaction, which is generally higher than standard credit card processing fees of around 2%.
Can BNPL work in physical retail stores as well as online?
Yes. BNPL can be integrated into POS systems as well as eCommerce platforms. Sensepass connects BNPL providers like Klarna and Afterpay to major retail POS environments, including Shopify POS and Oracle Xstore, for a consistent in-store and online checkout experience.
Recommended
- How to Offer Buy Now Pay Later: 2026 Retail Guide – Omnichannel payments at the Point Of Sale | Sensepass
- Essential Payment Gateway Selection Tips for Retailers – Omnichannel payments at the Point Of Sale | Sensepass
- How to Accept Klarna on Shopify POS Without Extra Hardware – Omnichannel payments at the Point Of Sale | Sensepass
- Afterpay Walmart Online: What Retailers Should Know – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

