
How to Enable BNPL Payments for Your Retail Store
July 15, 2026
TL;DR:
- Enabling buy now pay later payments helps retailers increase order value and conversion rates through installment options. Proper integration involves selecting the right provider, verifying platform compatibility, and setting up messaging across all sales channels. Patience in setup yields better operational results, higher sales, and flexible provider options.
Enabling BNPL payments, the industry term is “buy now pay later,” gives retailers a direct way to increase average order value and conversion rates by letting customers split purchases into installments. BNPL providers charge merchant fees ranging from 2% to 6% per transaction, higher than standard card fees, but the lift in completed purchases and basket size consistently offsets that cost. This guide covers every step retailers and eCommerce businesses need: prerequisites, technical integration, on-site promotion, operational management, and troubleshooting, with specific guidance for both online and in-store environments.
How to enable BNPL payments: prerequisites and preparation
Before you activate any BNPL option, you need to confirm three things: provider fit, platform compatibility, and fee structure. Skipping this step causes mismatches that are expensive to fix after launch.
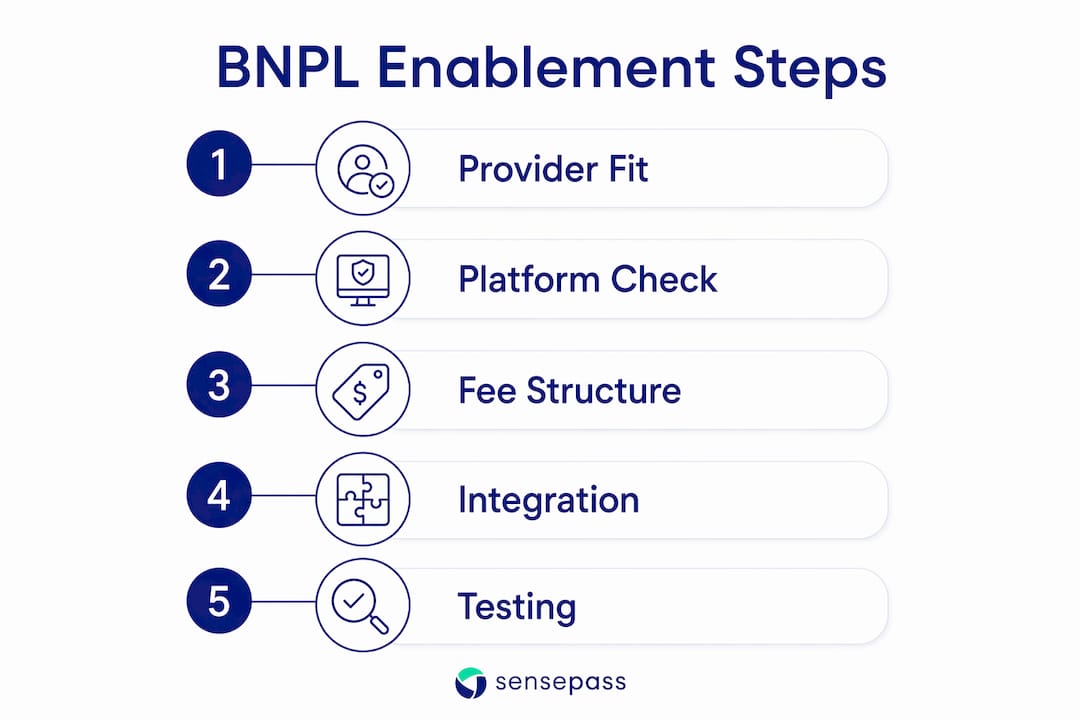
Choose the right BNPL provider for your customer base. Your average order value (AOV) determines which providers make sense. Providers like Klarna, Sezzle, ZIP, Splitit, and Afterpay each have different AOV sweet spots, approval rates, and geographic coverage. Match the provider to where your customers actually shop and what they typically spend.
Confirm platform compatibility before signing any merchant agreement. The BNPL integration must work with your existing eCommerce or POS platform. Sensepass connects with NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, Dynamics365, and more. Knowing your platform’s native support prevents costly custom development later.
Key prerequisites to check before setting up BNPL payments:
- Merchant account status: Your payment gateway must be active and in good standing.
- Platform plugin availability: Confirm the BNPL provider offers an official app or plugin for your platform.
- Fee modeling: Calculate whether the 2%–6% merchant fee is offset by your expected AOV increase.
- Credit risk handling: BNPL providers absorb the credit risk and pay you upfront minus fees. You do not chase the customer for repayment.
- Processor-agnostic gateway: A processor-agnostic platform like Sensepass, which supports 50+ card processors, gives you flexibility to add BNPL without replacing your existing processor.
| Prerequisite | What to verify |
|---|---|
| Platform compatibility | Official BNPL plugin exists for your eCommerce or POS system |
| AOV alignment | Provider’s minimum/maximum order limits match your typical basket size |
| Fee impact | Net margin holds after 2%–6% BNPL fee is applied |
| Gateway readiness | Your gateway supports redirect URLs and webhook endpoints |
| Hardware readiness | In-store terminals are reprogrammable or BNPL-compatible |
How do you integrate and activate BNPL in your retail systems?
Technical integration is where most retailers either get it right or create problems that surface weeks later. Follow these steps in order.
-
Apply for a merchant account with your chosen BNPL provider. Complete their onboarding, which includes business verification and agreement to their merchant terms. Approval typically takes one to three business days.
-
Install the official BNPL app or plugin for your platform. Native BNPL apps handle tokenization and regulatory disclosure better than third-party wrappers. Go directly to your platform’s app marketplace, not a generic plugin directory.
-
Add BNPL as a payment method in your dashboard. In Shopify Payments, for example, navigate to Settings > Payments > Alternative Payment Methods and activate your chosen provider. In WooCommerce, install the provider’s plugin and enter your API credentials under WooCommerce > Settings > Payments.
-
Configure on-site messaging widgets. Each BNPL provider supplies a JavaScript widget that displays installment pricing on product pages, cart drawers, and checkout. Paste the widget code into the correct template files or use the provider’s plugin settings panel.
-
Set up in-store BNPL via QR code or customer-facing terminal. In-store BNPL works best when customers apply on their own device in 10–30 seconds using a QR code displayed at the register. This removes staff from the credit application process and eliminates manual entry errors.
-
Whitelist redirect URLs and configure webhooks. Go to your BNPL provider’s developer dashboard and add your store’s confirmation and cancellation URLs. Set up webhook endpoints so your platform receives real-time order status updates.
-
Test across browsers and devices. Broken BNPL redirects on certain devices cause checkout failure and lost sales. Test on Chrome, Safari, Firefox, and Edge, on both desktop and mobile, before going live.
Pro Tip: Run a full end-to-end test transaction using a real card in sandbox mode. Confirm the order appears in both your platform’s order management system and the BNPL provider’s merchant portal before processing any live orders.
For Shopify POS specifically, Sensepass provides a direct BNPL connection for Shopify POS that handles the technical bridge between your POS terminal and BNPL providers without custom development.
What are the best practices to promote BNPL and drive customer adoption?
Getting BNPL live is step one. Getting customers to use it is where the revenue impact actually shows up.
The single biggest mistake retailers make is displaying BNPL only at checkout. Relying on a checkout badge alone leaves up to 40% of potential conversion lift uncaptured. Customers need to see installment pricing early, when they are deciding whether to add an item to their cart.
Display BNPL messaging at these three touchpoints:
- Product detail pages: Show the installment amount directly below the price. “4 payments of $24.75 with Klarna” is more persuasive than a generic badge.
- Cart drawer: Reinforce the installment option when customers review their cart. This is the moment they are most likely to reconsider a large purchase.
- Checkout: Confirm the option one final time. By this point, the customer has already been primed and is more likely to select BNPL.
Pro Tip: Use dynamic installment widgets that update in real time as customers change quantities or select product variants. Static messaging that shows a fixed installment amount for the wrong price creates confusion and erodes trust.
Sensepass unifies BNPL messaging across all retail touchpoints through its omnichannel payment platform, so your in-store and online messaging stays consistent. Track AOV, return rates, and conversion over a 90-day window after launch. That time frame gives you enough data to separate BNPL-driven lift from seasonal noise.
How do you manage BNPL payments operationally and handle returns?
Operational management is where BNPL gets complicated. The payment flow looks simple to the customer, but the back-end process involves a third party between you and the shopper.
BNPL providers pay you the full order amount upfront, minus their fee. The customer repays the provider directly. That means your cash flow is not affected by whether the customer makes their installments. However, return and refund workflows differ significantly from standard card transactions and require specific handling.
Key operational considerations for supporting BNPL in-store and online:
- Return windows: BNPL providers often have their own return policies that may not match yours. Communicate your BNPL-specific return policy clearly on your returns page and at the point of sale.
- Refund processing: Refunds go back through the BNPL provider, not directly to the customer’s card. Processing times vary by provider and can take longer than standard card refunds.
- Order status updates: Webhook failures can leave orders stuck in “pending” status. Set up automated cleanup rules to cancel abandoned BNPL orders after a defined window.
- Fraud detection: BNPL orders carry different fraud patterns than card orders. Configure your fraud detection layer specifically for BNPL transaction profiles.
- Staff training: In-store staff need to understand that they do not handle the credit application. Their role is to display the QR code and confirm the order once the customer completes the application on their own device.
Retailers who treat BNPL refunds the same as card refunds create customer service problems. The refund goes to the provider first, who then adjusts the customer’s installment schedule. Train your team on this distinction before go-live, not after the first complaint.
For managing BNPL refunds across channels, Sensepass provides a unified return flow that handles both online and in-store BNPL orders from a single dashboard.
What are the most common BNPL integration mistakes and how do you fix them?
Most BNPL problems fall into a small set of categories. Knowing them in advance saves significant time and revenue.
-
Using third-party BNPL wrappers instead of official plugins. Third-party wrappers often break compliance disclosures and disrupt tokenization. Always install the provider’s official app from your platform’s marketplace.
-
Skipping webhook configuration. Webhook failures leave orders in “pending” status indefinitely, blocking fulfillment. Verify every webhook endpoint returns a 200 response during testing.
-
Ignoring additional transaction fees. Some BNPL providers charge a fixed per-transaction fee on top of the percentage fee. Factor this into your margin calculations before launch, especially for low-AOV products.
-
Launching in-store without terminal verification. POS terminals need reprogramming or replacement to support BNPL flows. Confirm hardware compatibility with your processor before your go-live date.
-
Testing only on one browser or device. BNPL redirect flows behave differently across browsers. A flow that works on Chrome desktop may fail on Safari mobile. Test every combination your customers are likely to use.
Pro Tip: Build a pre-launch checklist that includes webhook response verification, a full sandbox transaction on at least four browser/device combinations, and a test refund. Run this checklist again after any platform update, since updates can silently break BNPL configurations.
Key Takeaways
Enabling BNPL payments requires provider selection, proper technical integration, and consistent on-site messaging across all touchpoints to capture the full conversion lift.
| Point | Details |
|---|---|
| Match provider to AOV | Choose a BNPL provider whose order limits align with your typical basket size. |
| Use official plugins only | Native BNPL apps handle tokenization and compliance better than third-party wrappers. |
| Surface messaging at three points | Show installment pricing on product pages, cart, and checkout to avoid losing 40% of conversion lift. |
| Prepare for BNPL refunds | Refunds route through the provider, not directly to the customer, requiring specific staff training. |
| Verify webhooks before launch | Webhook failures create stuck orders; test every endpoint and set up automated order cleanup. |
Why BNPL integration rewards patience over speed
I have worked with enough retailers to know that the ones who rush BNPL live are the ones calling about broken orders two weeks later. The technical setup is not the hard part. The hard part is the operational layer: training staff, configuring webhooks correctly, and building a return policy that accounts for the BNPL provider’s own timeline.
The fee question comes up in every conversation. Yes, 2%–6% is higher than a card fee. But the retailers who do the math honestly, comparing their pre-BNPL and post-BNPL AOV over 90 days, almost always find the conversion lift covers the cost. The ones who struggle are those who enable BNPL on low-margin products without adjusting their pricing strategy first.
The other thing I see consistently: retailers who treat BNPL as an online-only feature miss half the opportunity. In-store BNPL via QR code is genuinely fast and requires almost no staff involvement once the hardware is configured. Customers who might hesitate at a $400 purchase often complete it when they see a $100-per-month option on their phone at the register.
My honest recommendation is to choose a processor-agnostic platform from the start. Locking into a single processor limits your BNPL provider options later. Sensepass’s architecture, which supports 50+ card processors and providers including Klarna, Sezzle, ZIP, Splitit, and Afterpay, gives you room to add or swap providers as your business grows without rebuilding your payment stack.
— Vlad
Sensepass makes BNPL enablement practical for retailers
Retailers who want to activate BNPL without rebuilding their payment infrastructure get a direct path through Sensepass.
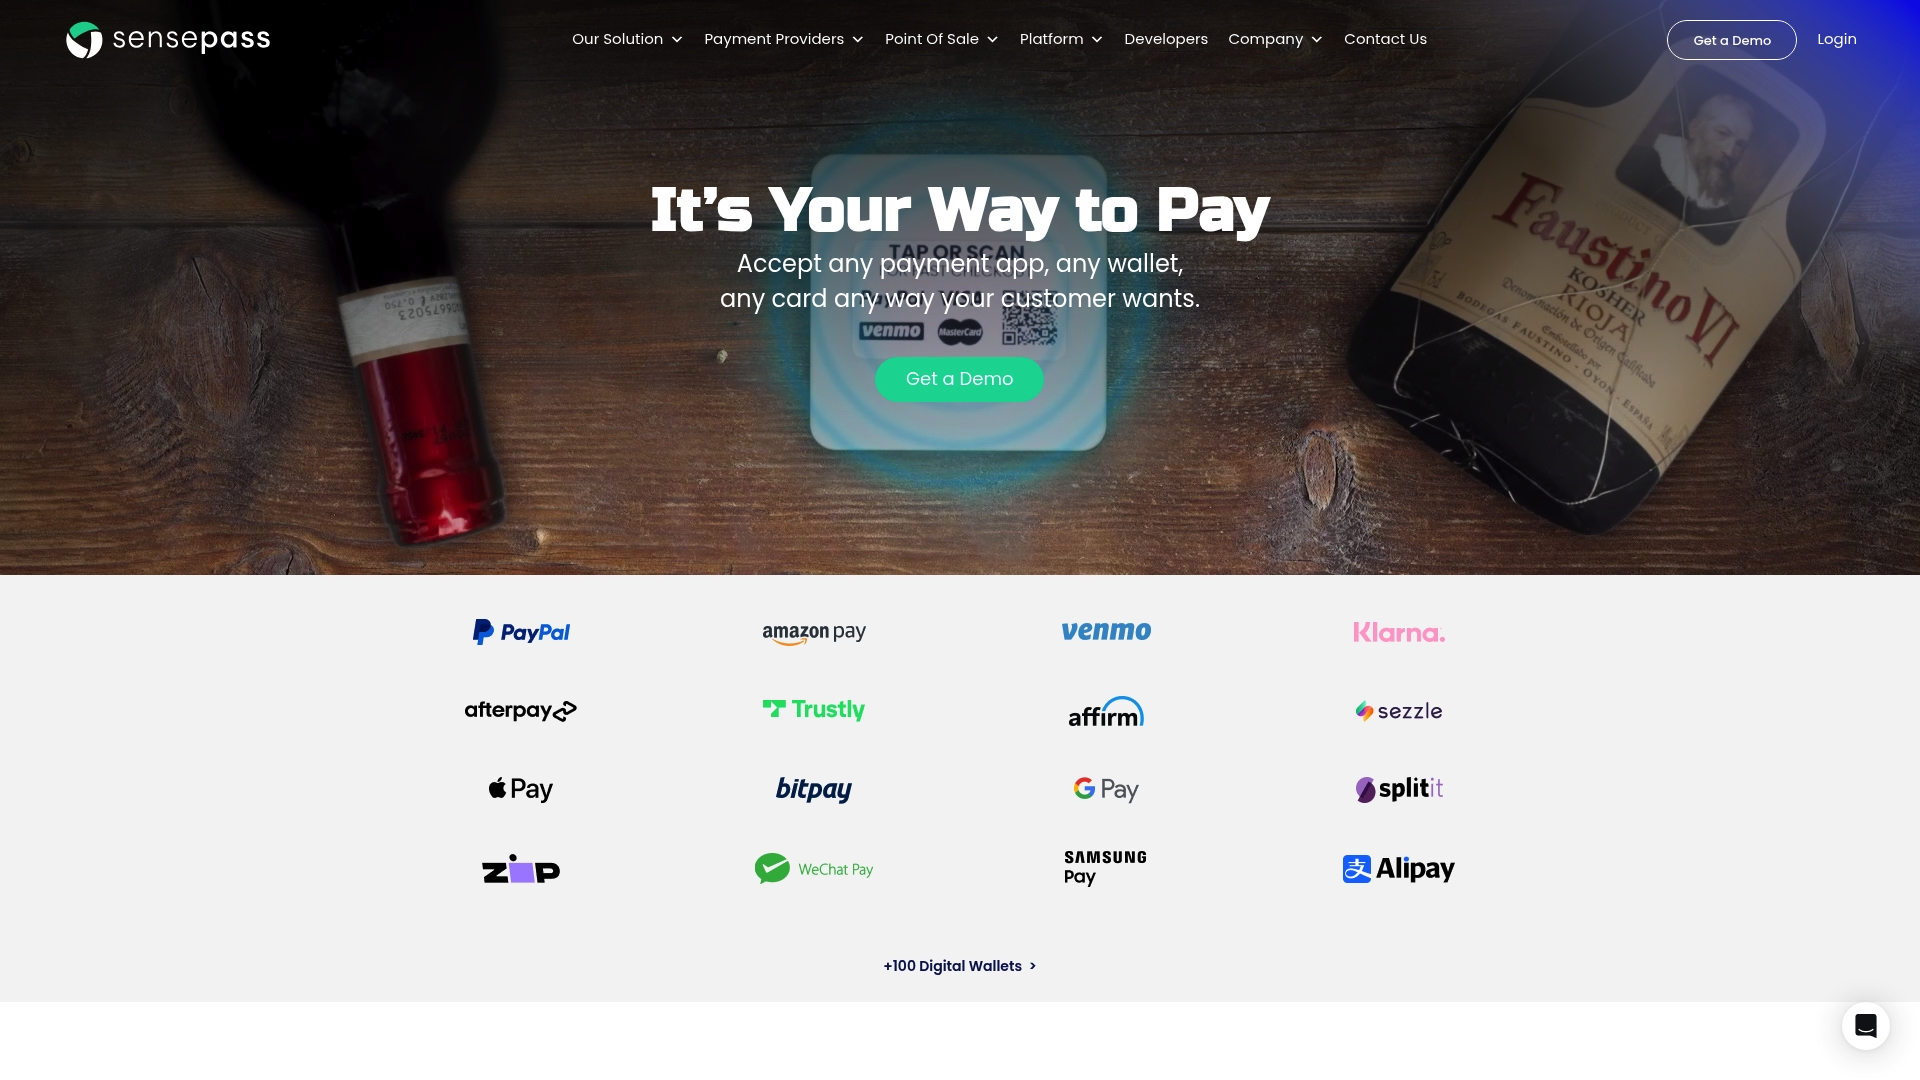
Sensepass connects with major platforms including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365. It supports BNPL providers Klarna, Sezzle, ZIP, Splitit, and Afterpay, plus financing options WeGetFinancing and Affirm. Digital wallets including PayPal, Venmo, Apple Pay, Google Pay, Alipay, Amazon Pay, and WeChat are also supported, alongside crypto payments via BitPay and Coinbase, and pay-by-bank options through Trustly and LinkMoney. Sensepass is processor-agnostic, giving you access to 50+ card processors for maximum flexibility. The full BNPL setup process for retailers is documented and supported end to end.
FAQ
What does it cost to enable BNPL payments?
BNPL providers charge merchant fees between 2% and 6% per transaction, which is higher than standard card fees. Most retailers offset this cost through higher average order values and improved conversion rates.
Do I need a new payment gateway to add BNPL?
Not necessarily. A processor-agnostic gateway like Sensepass supports BNPL providers alongside your existing card processors, so you can add BNPL without replacing your current payment setup.
How does in-store BNPL work at the point of sale?
In-store BNPL works best via QR code displayed at the register. The customer scans it, completes a credit application on their own device in 10–30 seconds, and the order is confirmed in your POS system.
How do BNPL refunds work for merchants?
Refunds on BNPL orders route through the provider, not directly back to the customer’s payment method. The provider adjusts the customer’s installment schedule, and processing times vary by provider.
Where should I display BNPL messaging on my website?
Display BNPL installment pricing on product detail pages, in the cart drawer, and at checkout. Showing it only at checkout leaves up to 40% of potential conversion lift uncaptured.
Recommended
- BNPL Payment Setup Process for Retailers: 2026 Guide – Omnichannel payments at the Point Of Sale | Sensepass
- How to Offer Buy Now Pay Later: 2026 Retail Guide – Omnichannel payments at the Point Of Sale | Sensepass
- Afterpay Walmart Online: What Retailers Should Know – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

