
Pay by Bank Integration: A Step-by-Step Business Guide
June 3, 2026
TL;DR:
- Pay by bank uses regulated PISPs to transfer funds directly from customers’ bank accounts within their banking apps, offering instant settlement and lower costs. Successful integration requires regulatory compliance, bank coverage mapping, and a technical setup involving redirects, consent, and webhooks. Ongoing monitoring and fallback options are crucial for maximizing adoption, ensuring reliability, and reducing operational risks.
Pay by bank is defined as a payment method that uses a regulated Payment Initiation Service Provider (PISP) to move funds directly from a customer’s bank account to a merchant, authenticated entirely within the customer’s banking app. The process for adding pay by bank options to your checkout is more structured than card integration but delivers real advantages: no card data to store, lower processing costs, and instant settlement via networks like the UK’s Faster Payments. This guide walks business owners and finance professionals through every stage, from technical prerequisites to operational optimization, using providers like Trustly, LinkMoney, and GoCardless as reference points.
What prerequisites are needed before adding pay by bank options?
Before you write a single line of integration code, three foundational requirements must be in place. Getting these right determines whether your rollout is smooth or plagued by edge cases from day one.
Regulatory and provider alignment
Adding bank payment methods starts with selecting a licensed PISP. A PISP is the regulated intermediary that connects your checkout to the customer’s bank via Open Banking APIs. Providers like Trustly and LinkMoney are established options with documented API workflows. You cannot initiate bank payments directly without routing through a licensed PISP. This is a legal requirement, not a technical preference.
Bank coverage mapping
Every PISP has a different list of supported banks by country and region. Coverage varies by provider and market, so you need to confirm that your target customer base banks with institutions your chosen provider supports. A provider with 90% coverage in the UK may cover only 40% of banks in another market. Map this before committing to an integration.
Technical readiness checklist
Your development team needs to be prepared for a different integration pattern than card payments. Key requirements include:
- Redirect and deep link handling so customers can move to their banking app and return to your checkout
- Consent wording that meets regulatory standards for payment authorization
- Webhook endpoints to receive asynchronous payment status updates
- Fallback payment method logic for customers whose banks are not yet supported
One significant benefit worth noting upfront: no card data is collected, which removes your checkout from PCI DSS card data scope. That reduction in compliance overhead is a real operational win for merchants of any size.
Pro Tip: Before starting integration, request a sandbox environment from your chosen PISP. Testing redirect flows, consent screens, and webhook delivery in a controlled environment will surface edge cases that would otherwise appear in production.
Sensepass supports in-store bank payment solutions and integrates with major POS platforms including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365, so your existing infrastructure is likely already compatible.
How to integrate pay by bank into your checkout flow
The step-by-step bank payment setup follows a consistent pattern across most PISP providers. The core flow has five stages, and each one requires deliberate design decisions.
Step 1: Add pay by bank as a selectable payment method
Display pay by bank alongside your existing options at checkout. Label it clearly. “Pay directly from your bank account” outperforms technical labels like “Open Banking Payment” in user testing. Position it near the top of your payment method list once adoption data supports it.
Step 2: Build the bank selection interface
After the customer selects pay by bank, present a list of supported banks drawn from your PISP’s coverage API. Sort by popularity in the customer’s region. Include a search field for customers with less common banks. If a customer’s bank is not supported, surface your fallback payment method immediately rather than letting them hit a dead end.
Step 3: Redirect for authentication
This is the defining step in the bank payment option integration process. Customers authenticate payments using biometric methods like Face ID or fingerprint within their own banking app, satisfying Strong Customer Authentication (SCA) requirements. Your checkout triggers a redirect or deep link to the banking app. The PISP manages the authorization handshake behind the scenes. Your job is to make the redirect feel intentional and the return to your site frictionless.
Step 4: Handle confirmation and fallback logic
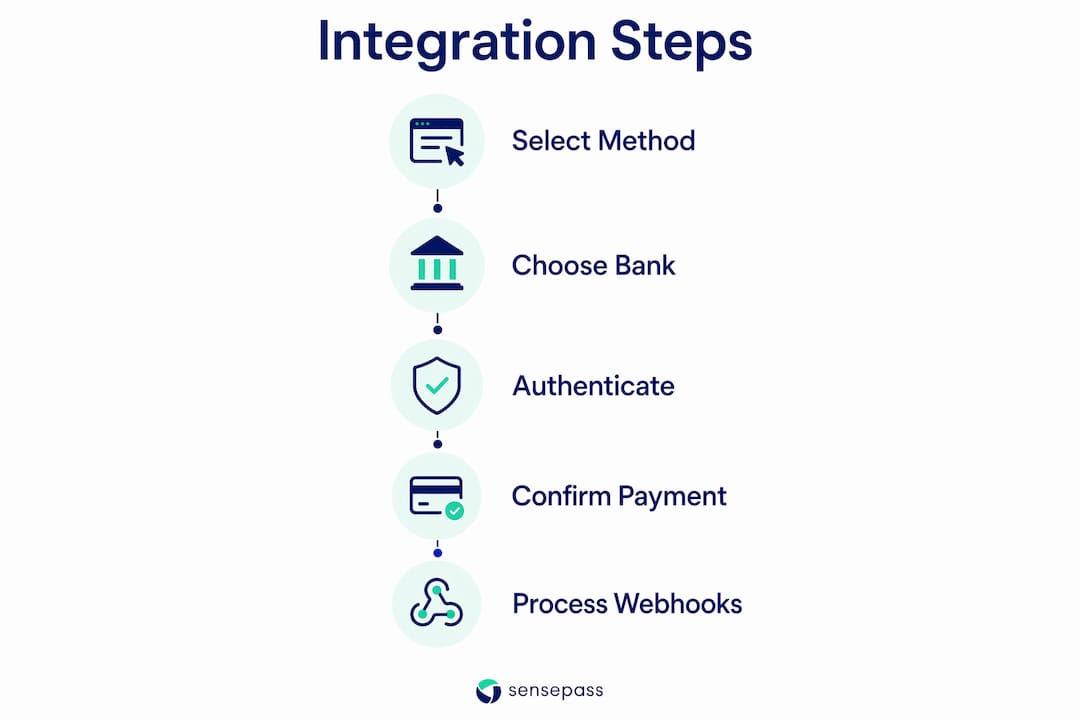
Once the customer approves the payment in their banking app, the PISP sends a confirmation signal. Payment status updates arrive asynchronously via webhook, meaning the customer may return to your site before the confirmation fires. Design your order confirmation page to handle a “pending” state gracefully while awaiting the webhook. Always have a fallback path ready.
Step 5: Process webhooks and fulfill orders
Webhook processing is where most integration failures occur. Build your webhook handler to be idempotent, meaning it can receive the same event multiple times without duplicating order fulfillment. Log every event with timestamps. Set up alerts for failed webhook deliveries.
| Integration step | Key action | Common failure point |
|---|---|---|
| Payment method display | Add to checkout UI with clear labeling | Poor label copy reduces selection rate |
| Bank selection | Render PISP coverage list dynamically | Static lists go stale as coverage changes |
| Authentication redirect | Deep link to banking app with return URL | Broken return URL strands customers |
| Confirmation handling | Show pending state, await webhook | Premature order confirmation before webhook |
| Webhook processing | Idempotent handler with logging | Duplicate fulfillment on retry events |
Pro Tip: Build a dedicated webhook testing script that replays real provider payloads against your handler. This catches serialization bugs and missing field errors before they affect live orders.
How do you troubleshoot and optimize pay by bank adoption?
Getting the integration live is step one. Driving actual adoption and maintaining reliability requires ongoing operational discipline. The following areas deserve consistent attention after launch.
Monitor coverage and participation actively
Bank participation in Open Banking networks changes. Banks add support, update their authentication flows, or temporarily suspend API access. Phased rollouts with active monitoring yield better operational stability than full launches with passive oversight. Check your PISP’s coverage changelog at least monthly and update your bank selection list accordingly.
Track conversion and failure rates by segment
Instrument your checkout to capture where customers drop off during the pay by bank flow. Useful metrics include: bank selection rate, redirect completion rate, authentication success rate, and webhook confirmation rate. Segment these by device type, because mobile users switching between apps have different drop-off patterns than desktop users opening a separate banking portal.
Balance fallback options to protect revenue
Until pay by bank reaches meaningful adoption in your customer base, a missing fallback is a revenue leak. Keep card payments and digital wallets like Apple Pay or Google Pay available alongside bank pay. Customers who encounter an unsupported bank or a failed authentication should land on an alternative payment screen within two clicks, not a dead end.
Stay current on consent and compliance requirements
Consumer protections for pay by bank align with existing digital payment regulations, covering unauthorized and incorrect transactions. Your consent wording must clearly identify the payee and the payment amount before the customer authorizes. Regulatory requirements in this area are active and subject to update, so treat your consent copy as a living document rather than a one-time setup task.
Refine the redirect and app-switching experience
The moment a customer leaves your checkout to authenticate in their banking app is the highest-risk point for abandonment. Test the full flow on iOS and Android across your top five supported banks. Confirm that deep links open the correct banking app rather than a browser fallback. Measure the time between redirect and return, and set a session timeout that gives customers enough time to complete authentication without leaving the order in limbo.
Pay by bank vs. other payment methods: what’s the real difference?
Understanding how bank pay compares to cards, digital wallets, and traditional transfers helps you position it correctly in your payment mix and set realistic expectations with your finance team.
Pay by bank eliminates card data handling entirely, which is the most structurally significant difference from card payments. No card PAN is stored or transmitted through your systems, which removes the most sensitive data category from your PCI DSS scope. That translates directly to lower compliance costs and a reduced attack surface.
Settlement speed is another meaningful distinction. Traditional bank transfers can take one to three business days. Pay by bank, routed through networks like Faster Payments, settles instantly after approval. For merchants managing cash flow tightly, that difference is material.
| Payment method | Card data required | Settlement speed | PCI DSS scope | Authentication method |
|---|---|---|---|---|
| Credit/debit card | Yes | 1 to 3 days | Full scope | CVV + 3DS |
| Pay by bank | No | Instant (via Faster Payments) | Reduced scope | Banking app biometrics |
| Digital wallet (Apple Pay, Google Pay) | Tokenized | 1 to 2 days | Reduced scope | Device biometrics |
| Traditional bank transfer | No | 1 to 3 days | Out of scope | Manual bank login |
The cost structure also differs. Card payments carry interchange fees, scheme fees, and processor margins. Pay by bank bypasses card networks entirely, which is why it is increasingly positioned as a cost-effective alternative for high-volume merchants. The authentication experience, using Face ID or fingerprint inside a trusted banking app, also tends to generate higher customer confidence than entering card details into a checkout form.
Key takeaways
The most reliable way to add pay by bank is to integrate with a licensed PISP, build idempotent webhook handling, and launch with a phased rollout focused on your highest-coverage banks first.
| Point | Details |
|---|---|
| Start with a licensed PISP | Select providers like Trustly or LinkMoney with documented API coverage in your target markets. |
| Reduce PCI scope immediately | No card data collection means your compliance burden drops from the first transaction. |
| Build for async payment status | Webhook handlers must be idempotent and logged to prevent duplicate order fulfillment. |
| Phase your rollout by bank coverage | Launch with supported banks first, then expand as provider coverage grows in your market. |
| Keep fallback methods active | Maintain card and wallet options until bank pay adoption stabilizes in your customer base. |
What I’ve learned from watching pay by bank rollouts succeed and fail
After working with merchants across retail and finance on payment integrations, the pattern I see most often is this: teams underestimate the operational layer and overestimate the technical layer. The API integration itself is not the hard part. Most PISP providers have solid documentation, and a competent developer can get a working redirect flow running in a few days. What trips teams up is everything that happens after the redirect.
Webhook reliability is where I’ve seen the most production incidents. A payment confirms in the banking app, the customer returns to the site, and the order never fulfills because the webhook arrived out of sequence or the handler threw an error on an unexpected field. These are not exotic edge cases. They happen regularly, especially in the first weeks after launch. The teams that handle this well are the ones who treat webhook processing as a first-class engineering concern, not an afterthought.
The other lesson I’d pass on is about fallback strategy. Some merchants resist keeping card payments active alongside bank pay because they want to push adoption. That instinct is understandable but counterproductive in the early stages. A customer who can’t complete a bank pay transaction and has no alternative is a lost sale. Give people an exit. You can gradually shift the default and the visual hierarchy toward bank pay as your data shows adoption growing.
The phased rollout approach is not just a risk management tactic. It’s also a learning mechanism. Starting with your top three or four supported banks gives you real conversion data before you scale. That data shapes every subsequent decision, from UX copy to timeout thresholds to which banks to prioritize in your selection list.
— Vlad
How Sensepass makes bank payment integration practical
Sensepass is built for merchants who need to add multiple payment methods without rebuilding their infrastructure for each one. For pay by bank specifically, Sensepass supports Trustly and LinkMoney out of the box, giving you access to established PISP coverage without managing separate provider relationships. The platform connects to major POS and commerce systems including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365.
Beyond bank pay, Sensepass supports digital wallets (PayPal, Venmo, WeChat, Apple Pay, Google Pay, Alipay, Amazon Pay), BNPL options (Klarna, Sezzle, ZIP, Splitit, Afterpay), financing through WeGetFinancing and Affirm, and crypto payments via BitPay and Coinbase. The platform is processor-agnostic, giving you access to 50+ card processors. If you’re building an omnichannel payment strategy that includes bank pay alongside your existing methods, Sensepass is designed to make that practical rather than painful.
FAQ
What is pay by bank and how does it work?
Pay by bank is a payment method where a regulated PISP connects your checkout to the customer’s bank via Open Banking APIs, and the customer authorizes the transfer inside their banking app using biometrics. Funds move directly from the customer’s account to yours, typically settling instantly through networks like Faster Payments.
Does adding pay by bank reduce PCI compliance requirements?
Yes. Because no card data is collected or transmitted through your systems, pay by bank removes the most sensitive data category from your PCI DSS scope, reducing compliance overhead compared to card payment processing.
What is a PISP and why do I need one?
A Payment Initiation Service Provider (PISP) is a regulated entity licensed to initiate payments on behalf of customers via Open Banking APIs. You cannot legally initiate bank payments directly without routing through a licensed PISP like Trustly or LinkMoney.
How do I handle customers whose banks are not supported?
Display a fallback payment method, such as card or digital wallet, immediately when a customer’s bank does not appear in your supported list. A clear, fast fallback path protects conversion rates while your provider’s bank coverage expands over time.
What is the biggest technical risk in a pay by bank integration?
Webhook processing is the highest-risk component. Payment status updates arrive asynchronously, meaning customers can return to your site before confirmation fires. Build idempotent webhook handlers with full event logging to prevent duplicate fulfillment and missed order confirmations.
Recommended
- How to integrate multiple payment gateways for retail – Omnichannel payments at the Point Of Sale | Sensepass
- How to start a payment processing business in 2026 – Omnichannel payments at the Point Of Sale | Sensepass
- Cashfree integration: Seamless setup for retail success – Omnichannel payments at the Point Of Sale | Sensepass
- Complete Retail Payment Integration Tutorial for 2025 – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

