
POS System Payment Routing Process: A Retail Guide
May 22, 2026
TL;DR:
- Effective payment routing within POS systems reduces declines, cuts costs, and maximizes revenue. Advanced logic evaluates transaction data and uses failover strategies to optimize approval rates and accommodate multiple payment methods seamlessly. Flexibility in routing and processor access, combined with continuous performance management, provides retailers a competitive edge in today’s dynamic payment landscape.
Every lost sale at the checkout counter has a story behind it. Often, that story is a payment decline that didn’t need to happen. The POS system payment routing process determines which processor handles each transaction, in what order, and under what conditions. Get it right, and you reduce declines, cut processing costs, and keep customers moving. Get it wrong, and you’re leaving revenue on the table every single day. This guide walks you through exactly how payment routing works inside a POS system, how to optimize it, and how to troubleshoot the most common failures.
Table of Contents
- Key Takeaways
- Understanding the POS System Payment Routing Process
- How the transaction lifecycle works step by step
- Optimizing payment routing for better approval rates and lower costs
- Common routing challenges and how to fix them
- My take on why routing flexibility is a competitive advantage
- How Sensepass handles payment routing for retail
- FAQ
Key Takeaways
| Point | Details |
|---|---|
| Routing logic runs in real time | Your POS evaluates BIN data, card type, and geography before each transaction to select the best processor. |
| Six stages define every transaction | From initiation through batching, each stage carries specific merchant responsibilities that affect settlement timing. |
| Cascading failover recovers lost sales | Automatic retries via alternative processors can recover 3 to 15% of declined transactions silently. |
| Approval rate beats cheapest cost | Routing to the lowest-cost processor at the expense of approval rates costs more in lost sales than it saves in fees. |
| Processor-agnostic platforms give flexibility | Solutions like Sensepass let you access 50+ processors and broad payment methods without lock-in. |
Understanding the POS System Payment Routing Process
Before you can optimize anything, you need to know what you’re working with. POS payment routing is not a single action. It’s a decision-making framework built from hardware, software, and real-time data that runs invisibly every time a customer taps, swipes, or dips a card.
Hardware and software components
A typical POS setup includes a terminal or card reader, a payment application, and a connection to a payment gateway. The gateway acts as the checkpoint that reads transaction data and decides where to send the authorization request. Behind that sits one or more payment processors, each with different approval rates, fee structures, and geographic strengths.
The software layer is where routing logic lives. Integrated POS systems with built-in payment orchestration can apply rules automatically. Basic standalone terminals usually route everything through one processor with no flexibility.
The data that drives routing decisions
Routing decisions rely on specific transaction data points:
- BIN (Bank Identification Number): The first six digits of a card identify the issuing bank, card type, and country of origin.
- Card type and network: Visa debit, Mastercard credit, and international cards each carry different interchange rates and routing requirements.
- Transaction amount: High-value transactions may trigger different routing rules or fraud thresholds.
- Geography: A card issued in Germany used at a U.S. store routes differently than a domestic transaction.
Supported payment methods matter
Modern retail payment workflows go far beyond card swipes. Businesses today need to accept digital wallets, BNPL options, bank transfers, and even crypto. Sensepass, for example, supports digital wallets including PayPal, Venmo, WeChat, Apple Pay, Google Pay, Alipay, and Amazon Pay. It also handles BNPL providers like Klarna, Sezzle, ZIP, Splitit, and Afterpay, along with financing options from WeGetFinancing and Affirm, crypto payments via BitPay and Coinbase, and pay-by-bank solutions through Trustly and LinkMoney.
POS platforms and payment method support
| POS Platform | Card Payments | Digital Wallets | BNPL | Processor Flexibility |
|---|---|---|---|---|
| Shopify POS | Yes | Yes | Limited | Limited |
| Oracle Xstore | Yes | Yes | Limited | Moderate |
| NCR | Yes | Yes | No | Limited |
| Sensepass Layer | Yes | Yes | Yes | 50+ processors |
| Aptos | Yes | Yes | Limited | Moderate |
Sensepass integrates with major platforms including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, Dynamics365, and more, bringing broad payment support to each of them.
How the transaction lifecycle works step by step
The payment lifecycle has six distinct stages: initiation, authorization, capture, clearing, settlement, and batching. Each one serves a specific function, and each one can fail in a specific way.
| Stage | What Happens | Merchant Responsibility |
|---|---|---|
| Initiation | Customer presents payment; POS captures transaction data | Confirm terminal reads the card correctly |
| Authorization | Gateway routes request to processor; issuing bank approves or declines | Monitor decline reason codes |
| Capture | Approved transaction is flagged for settlement | Confirm capture is not left pending |
| Clearing | Transaction data is sent to card networks for processing | Ensure data accuracy before submission |
| Settlement | Funds are transferred from issuing bank to merchant account | Verify settlement amounts against transactions |
| Batching | POS groups transactions and submits them for settlement | Close batches daily at a consistent time |
How routing logic selects a processor
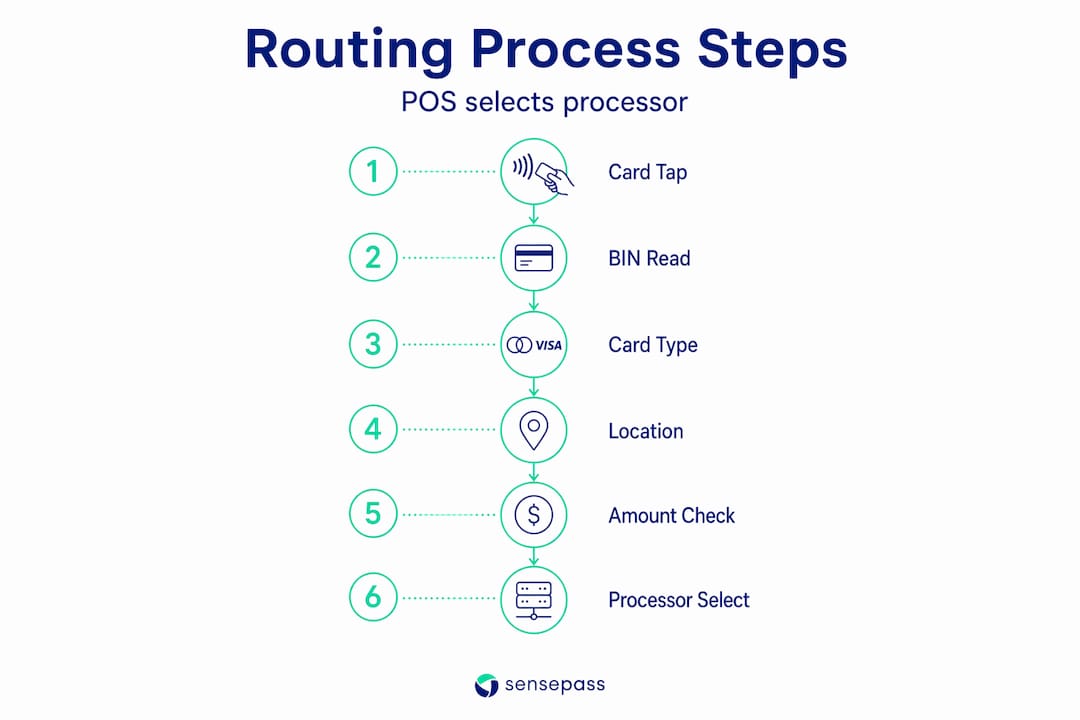
When a customer taps to pay, the gateway reads the BIN, evaluates the card type and geography, checks transaction amount against your routing rules, and selects a processor within milliseconds. Smart routing can improve approval rates by up to 20% by sending each transaction to the processor most likely to approve it, rather than defaulting to one processor for everything.
Cascading failover: the silent safety net
If your primary processor declines a transaction, cascading failover automatically retries it through a secondary or tertiary processor. The customer sees nothing. Cascading failover can recover between 3% and 15% of transactions that would otherwise appear as hard declines at the register.
Pro Tip: Close your POS batch at the same time each day, ideally after your last transaction. Authorization places a hold but does not move money. Pending batch closures block funds from reaching your account even when all transactions were approved.
Optimizing payment routing for better approval rates and lower costs
Once you understand the stages, you can start improving them. The most common mistake retailers make here is optimizing for the lowest processing fee instead of the highest approval rate. Higher decline rates cost more in lost sales and operational overhead than a few basis points saved on successful transactions.
Routing rules that actually work
Good routing rules are specific. A rule that says “use Processor A for all transactions” is not a routing strategy. Here’s what effective rules look like:
- Route international cards to a processor with strong cross-border approval rates, not to your default domestic processor.
- Route high-value transactions above $500 to a processor with higher authorization limits and lower fraud thresholds.
- Route debit cards through PIN-debit networks when available to reduce interchange costs.
- Route Apple Pay and Google Pay transactions through processors that support token-based authorization for better approval rates.
Machine learning and historical data
Advanced routing systems score each transaction before routing based on historical approval data. If Processor B has a 94% approval rate for Visa credit cards issued in France while Processor A has 78%, the system routes French Visa transactions to B automatically. This kind of intelligent payment path selection compounds over time as the system learns your transaction mix.
Payment orchestration platforms
Payment orchestration platforms centralize routing logic, tokenization, and retry handling into a single layer that sits between your POS and your processors. For complex retailers running multiple stores, channels, or geographies, this architecture removes processor lock-in and gives you the ability to add or switch processors without reconfiguring your POS. Sensepass operates exactly this way, giving merchants access to 50+ card processors through a single integration point.
Pro Tip: Never retry a hard decline through the same processor. Hard declines signal that the issuing bank rejected the transaction outright. Retrying the same path wastes time and may flag the card for fraud monitoring. Route to a different processor or prompt the customer to use an alternative payment method.
Here is a quick configuration checklist for retailers setting up or auditing their routing rules:
- Confirm your gateway supports multi-processor routing, not just single-processor connections.
- Map your transaction volume by card type and geography before writing routing rules.
- Set up automated retry logic with fallback processors for soft declines.
- Test routing rules in a sandbox environment before deploying to live terminals.
- Review approval rates by processor monthly and adjust rules based on performance data.
- Enable in-store payment optimization tools that track decline reason codes across processors.
Common routing challenges and how to fix them
Even well-configured systems run into problems. Knowing what to look for saves you hours of troubleshooting and prevents reconciliation nightmares.
Authorization versus settlement confusion
Authorization is risk approval; settlement is fund movement. A transaction can sit as “authorized” indefinitely if the batch never closes. This is one of the most common causes of cash flow timing issues for retail operators, and it often goes unnoticed until the weekly reconciliation shows a gap.
Terminal time synchronization
Misaligned clocks between your POS terminal and the backend server can trigger automatic declines across all card types. Processor security protocols require strict time alignment. This issue is frequently misdiagnosed as a network outage. If every terminal starts declining simultaneously with no obvious cause, check your system clock synchronization before calling your processor.
Reconciliation errors
Discrepancies in reconciliation often arise from refunds or partial authorizations processed after batch closure. These transactions appear in the next cycle’s reports, creating a mismatch between your POS totals and your processor settlement statement.
Common causes and fixes:
- Split batches: If a batch closes mid-shift, transactions split across two settlement periods. Fix by scheduling automated batch closes after business hours.
- Partial authorizations: Some cards (particularly prepaid) approve only part of a transaction amount. Confirm your POS software handles partial auth completion instead of voiding the remainder.
- Refunds processed late: Refunds issued after batch close appear in the next settlement cycle. Flag these in your reporting to avoid counting them as new discrepancies.
Pro Tip: Run a daily reconciliation report before closing the next batch. Compare your POS transaction log against your processor’s settlement report. Any mismatch of more than a few cents signals a problem worth investigating before it compounds.
Reconciliation mismatches rarely fix themselves. A $30 gap today can become a $3,000 audit problem in 90 days if refunds, partial auths, and split batches are not tracked and matched daily.
My take on why routing flexibility is a competitive advantage
I’ve worked with retailers across footwear, apparel, electronics, and grocery. The pattern I see consistently is that businesses obsess over processing fees while ignoring their decline rate. A merchant paying 2.1% per transaction with an 88% approval rate is losing more money than one paying 2.4% with a 96% approval rate. The math is straightforward once you put it on paper, but most operators never look at approval rate as a financial metric.
The second thing I’ve seen change outcomes significantly is cascading failover. In practice, the customers most likely to be affected by a decline at the register are also the ones least likely to try again. They leave. Automatic retries via alternative processors recover those sales without the customer knowing anything failed.
What I’ve learned from working across diverse retail environments is that the real value of a processor-agnostic platform is not just cost arbitrage. It’s the ability to add new payment methods, enter new markets, and respond to processor changes without rebuilding your POS integration from scratch. That kind of flexibility pays for itself the first time your primary processor has an outage and your fallback handles the load automatically.
The retailers I’ve seen get the most from their payment gateway selection treat routing as an ongoing performance management exercise, not a one-time configuration task.
— Vlad
How Sensepass handles payment routing for retail
Sensepass is built specifically for retailers who need more than a single-processor connection. As a processor-agnostic orchestration layer, Sensepass gives you access to 50+ card processors through one integration, with smart routing logic, cascading failover, and support for the full range of modern payment methods. That includes digital wallets like Apple Pay, Google Pay, PayPal, Venmo, WeChat, Alipay, and Amazon Pay; BNPL providers like Klarna, Afterpay, Sezzle, ZIP, and Splitit; financing through Affirm and WeGetFinancing; crypto via BitPay and Coinbase; and pay-by-bank through Trustly and LinkMoney.
Sensepass integrates natively with platforms including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365. If you’re ready to move from static routing to a flexible, performance-driven setup, explore Sensepass’s omnichannel payment solutions to see how it connects your entire retail operation.
FAQ
What is the POS system payment routing process?
The POS system payment routing process is the sequence of steps a payment takes from card presentation through processor selection, authorization, capture, and settlement. Routing logic determines which processor handles each transaction based on BIN data, card type, geography, and transaction amount.
How does cascading failover work in payment routing?
Cascading failover automatically retries a declined transaction through a secondary processor without customer involvement. It can recover 3 to 15% of transactions that would otherwise result in lost sales at the checkout.
Why does my POS show approved transactions that never settled?
This happens when a batch is not closed on time. Authorization approves the hold but does not move funds. Funds only transfer after the batch closes and settlement completes. Running an automated daily batch close at a fixed time prevents this issue.
What causes POS terminal declines that affect all card types at once?
Widespread simultaneous declines across all card types are often caused by clock synchronization issues between the POS terminal and the backend server. Processor security protocols reject transactions when timestamps don’t align, which is frequently misdiagnosed as a network failure.
What is the difference between a payment gateway and a payment orchestration platform?
A payment gateway connects your POS to a single processor or small set of processors. A payment orchestration platform sits above multiple gateways and processors, applying intelligent routing rules, managing retries, and centralizing tokenization across your entire payment stack.
Recommended
- Complete Guide to Retail Payment Workflow Process – Omnichannel payments at the Point Of Sale | Sensepass
- Retail Payment Workflow Optimization for Seamless Omnichannel Sales – Omnichannel payments at the Point Of Sale | Sensepass
- Master Payment Processing Best Practices for Your Business – Omnichannel payments at the Point Of Sale | Sensepass
- Seamless retail payment workflow: step-by-step guide – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

